Group Captive vs. Single Parent Captive:
When Is It Time to Leave the Harbor?

By Nichole McCabe

Group Captive vs. Single Parent Captive: Is It Time to Leave the Harbor?

One of the questions I get asked often is: “How do I know whether a group captive or a single parent captive is right for my company?” Or, for companies already participating in a group: “How do I know when it’s time to consider forming our own?”

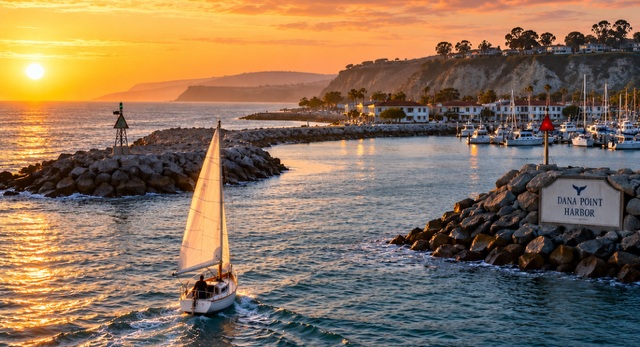
I think about it like boats in the ocean.

Imagine your business is a small boat operating in the traditional insurance market. You can operate your business safely and manage your own risk well for years, but you don’t control the weather. Catastrophe losses, social inflation, nuclear verdicts, carrier capacity, reinsurance pricing, and poor loss experience elsewhere in the market can eventually reach you, regardless of how well your own company performs. This is where we often see the best-in-class companies funding, at least in part, the performance of the worst-in-class.

A group captive moves that boat into a harbor. The weather hasn’t disappeared and the water can still get choppy, but now there are protections around you. Instead of being broadly pooled with the traditional market, you’re sharing risk with companies selected based on underwriting standards, loss performance, safety practices, and risk management.

For many businesses, that harbor may be exactly where they belong long term. A smaller company with relatively stable premium volume may never have the scale, capital, or economics to justify its own captive. That doesn’t make the group captive a stepping stone it failed to graduate from. It may simply be the right structure.

But some companies eventually outgrow the harbor.

A company may enter a group captive with $250,000 in casualty premium and, several years later, find itself approaching $1 million or more. Meanwhile, losses are improving, safety culture is stronger, management understands its risk better, and the company has greater financial capacity and appetite to retain that risk. Eventually, management may start asking: “Why are we still sharing this much risk with everyone else?”

There is no magic premium threshold or number of years that means it’s time to leave the harbor. In fact, leaving may not be the right answer at all. A company may continue using a group captive for certain lines while exploring a single parent captive for other risks where greater control, customization, or risk retention makes sense. But when scale, loss performance, risk management, financial capacity, and risk appetite have materially changed, it may be time to evaluate whether the company’s overall risk-financing strategy should evolve too.

And importantly, you don’t leave the harbor because the harbor failed. Sometimes the group captive did exactly what it was supposed to do. It helped the company develop a different relationship with risk and mature into an organization capable of taking greater control.

The goal isn’t necessarily simply to own a captive. It’s to finance risk through the structure, or combination of structures, that makes the most sense for the company you’ve become.

And sometimes the structure that got you here isn’t necessarily the structure that takes you where you’re going next.

What’s Happening Behind the Curtain? The Other Side of Insurance M&A

$17 billion. That’s a lot happening behind the curtain.

When I was a kid, my dad used to take my sister and me to Chuck E. Cheese. While everyone else was watching the animatronic band, I remember wondering what the heck was happening behind that curtain.

Apparently, I’ve been interested in operational infrastructure since I was eight.  Because decades later, I find myself asking the exact same question about mergers and acquisitions: What’s happening behind the curtain?

Aon’s announced $17 billion acquisition of USI is the latest chapter in what has become a remarkable period of consolidation across the insurance industry. We see the announcement, the purchase price, the strategy, the synergies and the opportunity. What we don’t see is the enormous operational undertaking required to make two organizations actually function as one.

Consolidation itself isn’t inherently good or bad. Scale can create tremendous resources, market access, technology and expertise. But integration is hard.

According to PwC’s M&A Integration Survey, just 14% of respondents reported significant integration success across strategic, financial and operational measures. PwC also found that successful integrations retained key employees at more than twice the level of less successful integrations, while systems and process integration remains among the most difficult areas to execute. And that matters because integration happens while everyone still has a day job.

Employees may be navigating systems that don’t quite talk to each other yet. Client data still has to remain accurate and cohesive. Operating models, reporting structures and processes are changing, while talented people continue managing existing accounts and relationships, sometimes with more on their desks than they can successfully manage.

McKinsey’s research reinforces the human side of that challenge. Across ten years of M&A survey data, organizational issues such as cultural differences and changes to operating models accounted, on average, for almost 50% of mergers failing to meet expectations. McKinsey notes that poorly managed organizational change can contribute to poor business performance, loss of critical talent and leakage of expected synergies. Talent deserves particular attention. During a transaction, some of the people most important to maintaining client relationships and institutional knowledge can also become vulnerable to outside opportunities. That means employee retention isn’t simply an HR issue. It can become an operational issue, a relationship issue and ultimately a client issue.

When integration doesn’t keep pace with acquisition, that burden can eventually reach the client experience too. Teams can become stretched thinner, response times can change, relationships can move and processes can become more complicated. As organizations become larger and more complex, I believe maintaining true solution neutrality becomes increasingly important. The better questions is, “What is the best solution for this client?” Not: “What is the best solution available within our platform?”

Anyone who knows me knows how I feel about one-size-fits-all risk solutions. That’s one of the reasons I’m so excited about what we’re building at Capterra Risk Solutions. We grow when our clients need us to. We listen because we can. We don’t begin with a product or structure and figure out how to make the client fit inside it. We begin with the business: its risks, objectives, people, appetite and where it wants to go. Sometimes the answer is a captive. Sometimes it isn’t. Sometimes it’s a structure we’ve used many times before, and sometimes the client requires something entirely different.

The insurance industry will continue to consolidate, and there are compelling reasons for it to do so. But as organizations get bigger, I believe something else becomes increasingly valuable: the ability to remain close enough to the client to hear what they’re actually saying.

Scale is powerful. So is attention. And clients shouldn’t have to wonder what’s happening behind the curtain.

Sources:

PWC Successful Mergers

McKninsey Cultural Change in Mergers

McKinsey Integrate Talent