
By Nichole McCabe
Group Captive vs. Single Parent Captive: Is It Time to Leave the Harbor?
One of the questions I get asked often is: “How do I know whether a group captive or a single parent captive is right for my company?” Or, for companies already participating in a group: “How do I know when it’s time to consider forming our own?”
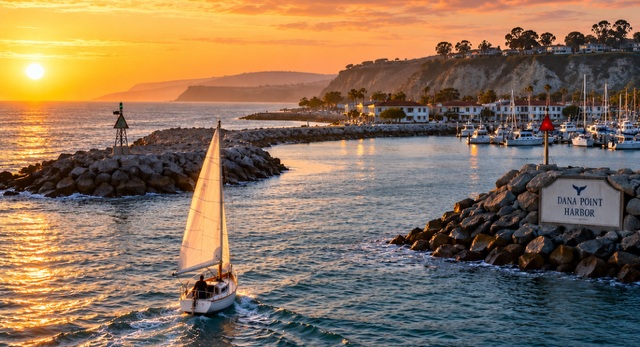
I think about it like boats in the ocean.
Imagine your business is a small boat operating in the traditional insurance market. You can operate your business safely and manage your own risk well for years, but you don’t control the weather. Catastrophe losses, social inflation, nuclear verdicts, carrier capacity, reinsurance pricing, and poor loss experience elsewhere in the market can eventually reach you, regardless of how well your own company performs. This is where we often see the best-in-class companies funding, at least in part, the performance of the worst-in-class.
A group captive moves that boat into a harbor. The weather hasn’t disappeared and the water can still get choppy, but now there are protections around you. Instead of being broadly pooled with the traditional market, you’re sharing risk with companies selected based on underwriting standards, loss performance, safety practices, and risk management.
For many businesses, that harbor may be exactly where they belong long term. A smaller company with relatively stable premium volume may never have the scale, capital, or economics to justify its own captive. That doesn’t make the group captive a stepping stone it failed to graduate from. It may simply be the right structure.
But some companies eventually outgrow the harbor.
A company may enter a group captive with $250,000 in casualty premium and, several years later, find itself approaching $1 million or more. Meanwhile, losses are improving, safety culture is stronger, management understands its risk better, and the company has greater financial capacity and appetite to retain that risk. Eventually, management may start asking: “Why are we still sharing this much risk with everyone else?”
There is no magic premium threshold or number of years that means it’s time to leave the harbor. In fact, leaving may not be the right answer at all. A company may continue using a group captive for certain lines while exploring a single parent captive for other risks where greater control, customization, or risk retention makes sense. But when scale, loss performance, risk management, financial capacity, and risk appetite have materially changed, it may be time to evaluate whether the company’s overall risk-financing strategy should evolve too.
And importantly, you don’t leave the harbor because the harbor failed. Sometimes the group captive did exactly what it was supposed to do. It helped the company develop a different relationship with risk and mature into an organization capable of taking greater control.
The goal isn’t necessarily simply to own a captive. It’s to finance risk through the structure, or combination of structures, that makes the most sense for the company you’ve become.
And sometimes the structure that got you here isn’t necessarily the structure that takes you where you’re going next.